Week commencing November 2nd 2026
TradeDay Macro Matters
Macroeconomic / Geopolitical developments
- Headline US stock averages fall, as US Treasuries rally
- Fed leaves rates unchanged (as do the ECB and BoJ)
- Big Tech earnings flash warning signs
- GDP and PCE show economic resilience but inflationary risks
- Another big week ahead with global PMI and US Employment data, US Midterm Elections, plus earnings from Apple, Palantir and AMD
- What's Ahead
Headline US stock averages fall, as US Treasuries rally
US stock markets ended the week lower, reversing early gains as renewed concerns surrounding Artificial Intelligence investment triggered a sharp sell-off in technology shares. The Nasdaq Composite fell 2.00%, while the S&P 500 declined 0.57% and the Dow Jones Industrial Average lost 0.85%. Small and mid-cap stocks proved more resilient, gaining 1.08% and 0.84% respectively, while value stocks outperformed growth stocks.
In contrast, US Treasuries attracted demand as investors moved towards safer assets amid the technology sell-off. The 10-year Treasury yield fell from around 5.00% to approximately 4.94%, while the two-year yield declined from 4.69% to around 4.56%. The move marked a notable reversal in bond yields towards the end of the week, with investors reassessing the risks surrounding highly valued technology companies and their substantial AI investment plans.
Fed leaves rates unchanged (as do the ECB and BoJ)
The Federal Reserve kept interest rates unchanged at 3.75% to 4.00% at its October meeting, following September's rate increase. The decision was supported by 10 of the 12 voting members, with two policymakers dissenting in favour of a further 0.25 percentage point hike. The Fed upgraded its assessment of economic activity, describing growth as proceeding at a strong pace, but continued to highlight that inflation remains elevated. Chair Kevin Warsh offered limited guidance on the timing of any further rate increases, emphasising that future decisions will depend on incoming economic data.
Elsewhere, the European Central Bank and Bank of Japan also left interest rates unchanged. The ECB maintained its deposit rate at 2.50%, acknowledging that rising energy prices pose further risks to inflation while potentially weighing on economic growth. The Bank of Japan held its policy rate at 1.25%, but indicated that underlying inflation was now broadly consistent with its 2% target for the first time since the target was introduced in 2013. Both central banks maintained a cautious approach, leaving the possibility of further policy changes dependent on economic and inflation developments.
Big Tech earnings flash warning signs
Quarterly results from some of the world's largest technology companies reignited concerns about the scale and sustainability of Artificial Intelligence investment. Alphabet shares suffered a particularly sharp decline after the company missed revenue and earnings expectations, while reporting negative free cash flow of approximately $9.1 billion. Although its cloud division delivered strong growth, investors were unsettled by the significant spending required to expand its AI infrastructure and management's warning that capital expenditure will increase substantially again in 2027.
Amazon also disappointed investors after missing earnings and revenue expectations, with its substantial AI investment contributing to a negative free cash flow position of $42.4 billion. Its AWS cloud division remained a bright spot, growing revenue by 39%, but the results did little to reassure markets about the returns from its spending plans. Microsoft delivered a more positive set of results, with revenue growth of 19% and Azure cloud growth of 48%, although free cash flow also declined. Meanwhile, Intel shares plunged nearly 29% on Friday following a disappointing outlook. Overall, investors are becoming increasingly selective, demanding clearer evidence that the enormous sums being invested in AI will translate into sustainable revenue, earnings and cash generation.
GDP and PCE show economic resilience but inflationary risks
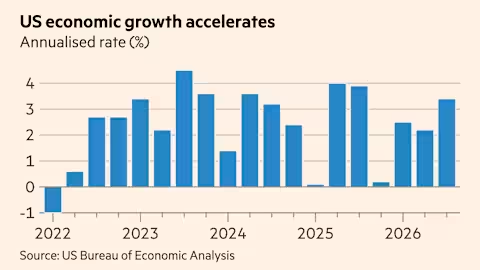
US economic data offered further evidence of resilience, with third-quarter GDP growing at an annualised rate of 3.4%, comfortably ahead of economists' expectations of 3.1% and accelerating from the previous quarter's 2.2% growth. Consumer spending remained supportive, increasing by 0.5% in September, although personal income growth was more modest at 0.2%. The figures suggest that the US economy continues to expand at a healthy pace despite higher energy costs and wider economic uncertainty.
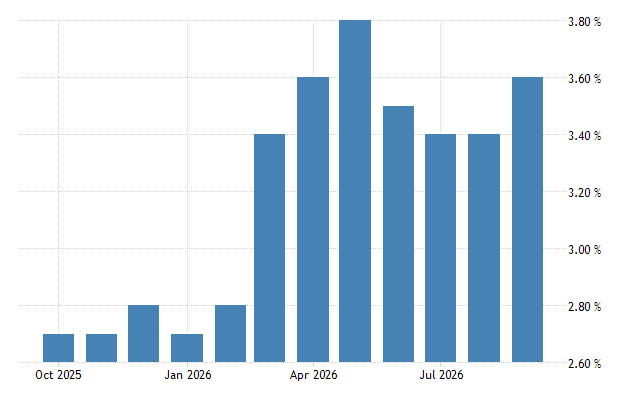
However, inflation remains a significant concern for policymakers. The Federal Reserve's preferred measure, the Personal Consumption Expenditures (PCE) Price Index, increased to 3.6% year on year in September, up from 3.4% in August. Core PCE, which excludes food and energy, also edged higher to 3.1%, remaining well above the Fed's 2% target. With energy prices continuing to put pressure on household and business costs, the combination of resilient economic growth and persistent inflation leaves the Federal Reserve facing a difficult balancing act.
Another big week ahead with global PMI and US Employment data, US Midterm Elections, plus earnings from Apple, Palantir and AMD
Markets face another eventful week, with the US Midterm Elections taking place on Tuesday, 3 November. Investors will be watching closely as the results determine control of Congress and could influence the direction of government policy, including taxation, spending and regulation. Economic data will also be in focus, particularly the October US Employment Report on Friday, with Non-farm Payrolls expected to increase by around 60,000, following September's relatively weak gain of 29,000. The Unemployment Rate is forecast to remain at 4.2%. Global manufacturing and services PMI releases, including the latest US ISM surveys, will provide further insight into the health of the global economy.
On the corporate front, earnings from Apple and Palantir are due on Monday, followed by AMD on Tuesday, with Qualcomm and several other major companies also reporting during the week. Investors will be looking for updates on consumer demand, AI adoption and the ability of technology companies to turn investment into profitable growth. Apple's iPhone sales and services performance will be important, while AMD's data centre business will attract particular attention as investors assess its position in the AI chip market. With the midterm elections, employment figures and another significant round of earnings all on the calendar, markets could remain volatile as November gets underway.
What's Ahead
Central Bank Watch: Central bank activity this week will focus on the Reserve Bank of Australia, which announces its Monetary Policy Statement and Interest Rate Decision on Tuesday, followed by the Bank of England’s Monetary Policy Statement, Interest Rate Decision, Minutes and Press Conference on Thursday.
Macro Data Watch: The main macro data releases this week are the global PMI data on Monday and Wednesday as well as the US Employment Reports on Friday. Some other releases of note are EU HICP on Wednesday, EU Retail Sales and Canadian Employment Reports both on Friday.
Earnings Watch: The Q3 US earning season continues this week with key stand out releases from Apple, one of the Magnificent Seven on Monday, Palantir also on Monday and AMD on Tuesday.
US came off US Daylight Saving Time on Sunday 1st November
US Midterm Elections are on Tuesday 3rd November
Date
Major Macro Data
11/02/2026
Global Manufacturing PMI; German Retail Sales
11/03/2026
RBA Monetary Policy Statement, Interest Rate Decision and Press Conference; US Factory Orders and JOLTS Job Openings
11/04/2026
Global Service and Composite PMI; EU HICP; US ADP Employment Change
11/05/2026
BoJ Monetary Policy Meeting Minutes; German Factory Orders; EU PPI; BoE Monetary Policy Statement, Interest Rate Decision, Minutes and Press Conference; US Challenger Job Cuts, Initial Jobless Claims, Nonfarm Productivity and Unit Labor Costs
11/06/2026
German Industrial Production; EU Retail Sales; Canadian Employment Reports; US Employment Reports, Michigan Consumer Sentiment Index and Consumer Inflation Expectations
Date
Major Earnings Data
11/02/2026
Apple; Berkshire Hathaway B; Palantir Tech; Vertex; Williams; Fox Corp
11/03/2026
AMD; Amgen; Arista Networks; Shopify Inc; Pfizer; Eaton; Marathon Petroleum; Booking
11/04/2026
Arm ADR; McDonald’s; Qualcomm; Uber; McKesson
11/05/2026
ConocoPhillips; Airbnb
11/06/2026
Nothing of note
