Week commencing November 16th 2026
TradeDay Macro Matters
Macroeconomic / Geopolitical developments
- US stocks rally in volatile week
- Jensen Huang’s Nvidia departure cannot halt broader AI rebound
- US CPI inflation data hotter than expected
- US Treasury yields reverse higher amid inflation fears
- Upcoming Nvidia results, FOMC Minutes and US Retail Sales the standouts in a data light week
- What's Ahead
US stocks rally in volatile week
US stock markets finished the week firmly higher, recovering some of the losses suffered during the recent technology-led sell-off. The S&P 500 gained 2.51%, the Nasdaq Composite rose 2.27%, and the Dow Jones Industrial Average advanced 2.1%, marking the strongest weekly performance for the major indices since early August. However, trading remained unsettled, with gains narrowing towards the end of the week as concerns about inflation, rising Treasury yields and volatility in AI-related shares weighed on sentiment.
The rally was supported by strength across several areas of the market, suggesting that the recovery extended beyond the largest technology companies. Energy was the best-performing sector, gaining 5.53%, followed by industrials, which rose 3.79%. Mid-cap stocks also outperformed their larger counterparts, climbing 3.01%, while small-cap stocks gained 1.92%. Elsewhere, European and Japanese equities also recorded strong weekly gains, although Chinese markets struggled as technology shares came under pressure.
Jensen Huang’s Nvidia departure cannot halt broader AI rebound
Artificial intelligence stocks staged a broader recovery during the week, supported by renewed optimism surrounding demand for computing infrastructure and encouraging developments across the industry. Strong sales growth from Taiwan Semiconductor Manufacturing and better-than-expected results from AI cloud provider CoreWeave helped restore some confidence following the previous week's sell-off. However, the recovery was far from universal, with Nvidia becoming the centre of attention after its co-founder and chief executive, Jensen Huang, resigned on Thursday following reports concerning his personal conduct and relationships.
Nvidia shares fell approximately 13% over the week as investors reacted to the leadership uncertainty, with its departure announcement adding further pressure to an already unsettled AI trade. Nevertheless, the wider semiconductor sector proved more resilient, with the Philadelphia Semiconductor Index gaining approximately 8%, while the S&P 500 also advanced 2.51%. This divergence suggests that investors were able to look beyond Nvidia's difficulties and continue to find opportunities elsewhere in the AI sector, although uncertainty surrounding the company's future leadership remains a significant concern.
US CPI inflation data hotter than expected
US inflation proved stronger than economists had anticipated in October, raising fresh concerns about the Federal Reserve's ability to bring price pressures under control. The Consumer Price Index increased by 0.4% month on month, above forecasts of 0.3%, although this represented a slowdown from September's 0.6% rise. Core CPI, which excludes food and energy prices, also exceeded expectations, increasing by 0.3% against forecasts of 0.2%. The Bureau of Labor Statistics did not publish an annual inflation figure, as last year's government shutdown prevented the collection of comparable October 2025 data.
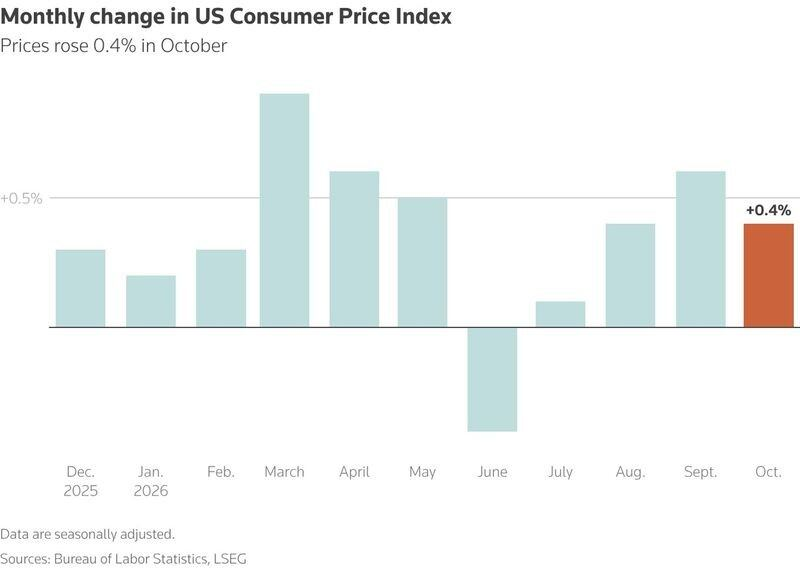
The figures suggested that inflationary pressures remain widespread, with increases across areas including food, shelter, transportation and medical care. Shelter costs rose by 0.3%, accounting for more than 30% of the overall monthly increase, while food prices climbed 0.5%. The stronger-than-expected report reinforced expectations that the Federal Reserve may need to tighten monetary policy further, with markets moving to fully price in a quarter-point interest rate increase at the December meeting. Some investors also began considering the possibility of a larger half-point increase.
US Treasury yields reverse higher amid inflation fears
US government bond yields moved sharply higher during the week as investors reassessed the outlook for interest rates following the stronger inflation figures. The 10-year Treasury yield climbed from approximately 4.86% to 5.15%, while the more policy-sensitive two-year yield increased from 4.51% to 4.88%. This represented a particularly significant weekly move, reversing the recent decline in yields and placing renewed pressure on bond prices.
Hawkish comments from Federal Reserve officials added to the upward pressure, with several policymakers suggesting that further rate increases may be necessary to bring inflation closer to the central bank's 2% target. Although October's Producer Price Index provided some relief, rising by 0.3% month on month compared with expectations of 0.4%, the annual headline rate accelerated to 6.5%. Markets are fully pricing in a December rate increase, while expectations of a larger move have also increased. Higher borrowing costs could create further challenges for businesses and consumers, while also placing pressure on equity valuations.
Upcoming Nvidia results, FOMC Minutes and US Retail Sales the standouts in a data light week
Attention now turns to another important week for financial markets, with Nvidia's third-quarter results expected to be the main corporate event. The chipmaker is scheduled to report on Tuesday, with analysts forecasting revenue of approximately $109 billion and earnings per share of around $2.47. Given the recent uncertainty surrounding its leadership, investors will be looking beyond the headline figures for reassurance about future demand for AI chips, profit margins and the company's outlook under interim chief executive Colette Kress. The results could have implications for the wider technology sector, particularly other companies involved in AI infrastructure.
On the economic calendar, Tuesday's US Retail Sales figures will provide an important update on consumer spending, following September's stronger-than-expected increase of 0.8%. Investors will also examine the Federal Reserve's October Meeting Minutes, due on Wednesday, for further insight into policymakers' decision to leave interest rates unchanged and their appetite for further tightening. With inflation remaining elevated and markets increasingly expecting a December rate increase, the Minutes could influence expectations for the Fed's next move. Together, these events are likely to keep attention firmly on the outlook for AI investment, the strength of the US consumer and the future direction of interest rates.
What's Ahead
Central Bank Watch: It is a busier week for central bank activity, the main release will be the Federal Open Market Committee Minutes on Wednesday. Some other releases of note are the Reserve Bank of Australia Meeting Minutes on Tuesday and People’s Bank of China Interest Rate Decision on Friday.
Macro Data Watch: The main macro data release this week is US Retail Sales on Tuesday. Some other releases of note are Canadian CPI on Monday, UK Employment Reports on Tuesday and UK CPI on Wednesday.
Earnings Watch: The final releases from the Q3 US earning season come out this week, with the main release being Nvidia on Tuesday. Some other releases of note are Home Depot, Walt Disney, Target and Walmart.
Date
Major Macro Data
11/16/2026
Japanese GDP; Chinese Industrial Production and Retail Sales; EU Industrial Production; Canadian CPI
11/17/2026
RBA Meeting Minutes; UK Employment Reports; US Retail Sales and Industrial Production
11/18/2026
Japanese Trade Reports; UK CPI, PPI and RPI; EU HICP; US Building Permits, Housing Starts and Pending Home Sales; FOMC Minutes
11/19/2026
German Buba Monthly Report; US Initial Jobless Claims
11/20/2026
Japanese CPI; UK Consumer Confidence and Retail Sales; PBoC Interest Rate Decision; German PPI; Canadian Retail Sales; EU Consumer Confidence; US Michigan Consumer Sentiment Index and Consumer Inflation Expectations
Date
Major Earnings Data
11/16/2026
Nothing of note
11/17/2026
Nvidia; Home Depot; Walt Disney
11/18/2026
Palo Alto Networks; TJX; Lowe’s; Target
11/19/2026
Walmart; PDD Holdings DRC; Intuit
11/20/2026
Nothing of note
