Week commencing October 12th 2026
TradeDay Macro Matters
Macroeconomic / Geopolitical developments
- US stock averages make choppy gains and hit record highs
- Oil prices chop higher with ongoing Middle East tensions
- Fed Minutes point to rate hikes, as UST yields retreat from multi-decade highs
- Focus this week on the start of Q3 earnings and US CPI
- What's Ahead
US stock averages make choppy gains and hit record highs
US stock markets finished the week higher despite a choppy trading pattern, with the S&P 500 gaining 1.15%, the Dow Jones Industrial Average rising 0.93% and the Nasdaq Composite advancing 0.64%. The S&P 500 and Nasdaq reached record highs on Tuesday before pulling back midweek, with technology shares later recovering from a sharp selloff to help lift the major indexes into Friday’s close.
Performance varied across the market, with utilities gaining 3.92% and consumer defensives rising 3.89%, while industrials fell 0.87% and technology edged down 0.13% for the week. Smaller companies continued to lag, with small cap stocks up just 0.19%, compared with gains of 1.17% for large caps and 1.95% for mid caps, as investors remained cautious about the impact of elevated borrowing costs.
Oil prices chop higher with ongoing Middle East tensions
Oil prices ended the week modestly higher after fluctuating sharply in response to developments in the Middle East. Renewed attacks on commercial vessels around the Strait of Hormuz raised concerns about the security of global energy supplies, with Brent crude briefly moving above $105 a barrel on Thursday before retreating as President Donald Trump said the US would not attack Iran before November’s midterm elections.
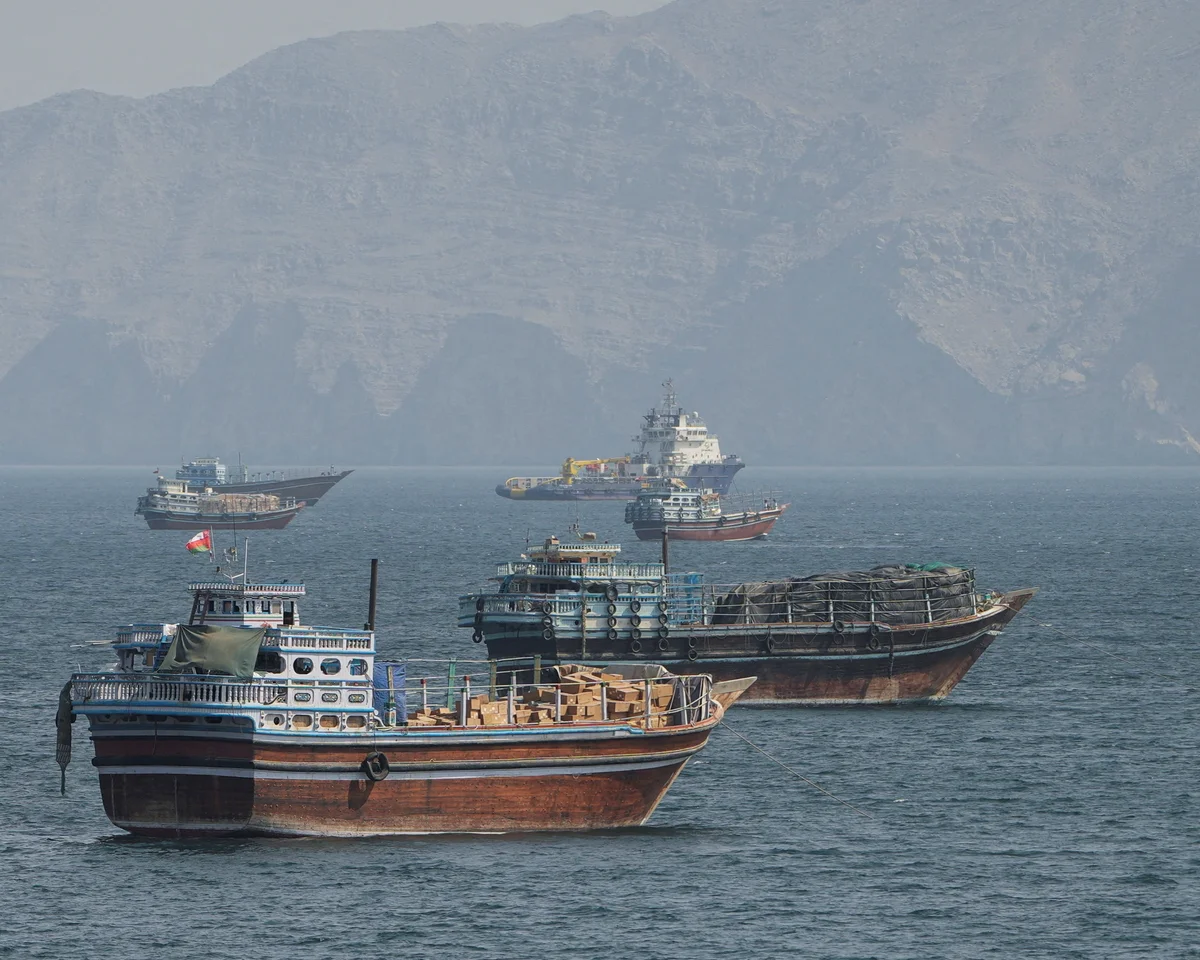
Supply concerns were compounded by Hurricane Isaias, which threatened offshore production and refining operations along the US Gulf Coast, prompting companies to shut in around 500,000 barrels per day of production. Although prices remained below the highs reached earlier in the conflict, continued disruption to shipping routes and energy infrastructure kept geopolitical risk firmly in focus and left markets sensitive to further developments.
Fed Minutes point to rate hikes, as UST yields retreat from multi-decade highs
Minutes from the Federal Reserve’s September meeting indicated that most policymakers considered another interest rate increase appropriate before the end of the year, reflecting concerns that inflation could remain persistently above target. Officials also highlighted the risk that higher energy costs and strong demand linked to artificial intelligence could feed into broader price pressures, although the minutes offered little clarity on the timing of any further move and emphasised that decisions would depend on incoming economic data.
Treasury yields retreated slightly by the end of the week after reaching fresh multi decade highs, with the 10 year yield easing to 5.24% from 5.28% and the 2 year yield falling to 4.80% from 4.83%. However, borrowing costs remained elevated, while softer employment data reduced expectations of an immediate October rate increase, leaving investors to weigh the possibility of further tightening later in the year against signs of a more gradual approach.
Focus this week on the start of Q3 earnings and US CPI
The third quarter earnings season gathers pace this week, with major US banks including JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo among the first to report. Investors will look beyond headline profits to assess lending activity, credit quality and net interest income, while results from semiconductor companies ASML and Taiwan Semiconductor Manufacturing will offer further insight into the strength of AI related demand and the sustainability of investment in the sector.
The main economic event is Wednesday’s US Consumer Price Index report for September, with headline inflation forecast to accelerate to 3.6% annually from 3.4% in August and monthly inflation expected to rise to 0.6%. The figures could influence expectations for the Federal Reserve’s next policy decision later in October, while Thursday’s Producer Price Index and Retail Sales data will provide additional clues on business costs and consumer demand. With stocks near record highs and Treasury yields still elevated, stronger than expected inflation could put renewed pressure on markets.
What's Ahead
Central Bank Watch: It is a relatively quiet week on the central bank front, with the only major release being the RBA Meeting Minutes on Tuesday. Instead, investor focus will be on speeches from officials at the Fed, ECB, BoE and BoC for any fresh signals on the interest rate outlook.
Macro Data Watch: The main macro data release this week is the US CPI on Wednesday. Some other releases of note are the German HICP on Tuesday, Chinese CPI on Wednesday, US Retail Sales and PPI both on Thursday.
Earnings Watch: The Q3 US earning season kicks off this week with major US banks reporting alongside J&J, ASML and Taiwan Semiconductor.
Date
Major Macro Data
10/12/2026
Nothing of note
10/13/2026
UK Retail Sales; RBA Meeting Minutes; German HICP; US Existing Home Sales Change and Monthly Budget Statement
10/14/2026
Chinese CPI, PPI and Trade Reports; US CPI and Fed Beige Book
10/15/2026
UK GDP, Industrial Production and Manufacturing Production; EU Industrial Production; US Retail Sales, PPI, Initial Jobless Claims; NY Empire State Manufacturing Index and Philadelphia Fed Manufacturing Survey
10/16/2026
US Industrial Production; EU HICP
Date
Major Earnings Data
10/12/2026
Louis Vuitton; Progressive
10/13/2026
JPMorgan; J&J; UnitedHealth; Goldman Sachs; Wells Fargo&Co; Citigroup; Rio Tinto ADR; Domino’s Pizza
10/14/2026
ASML ADR; Bank of America; Morgan Stanley; BlackRock
10/15/2026
Taiwan Semiconductor ADR; Charles Schwab; Interactive Brokers; Prologis
10/16/2026
Schneider Electric