Week commencing February 5th 2024
TradeDay Macro Matters
Macroeconomic / Geopolitical developments
- US Stocks Up Again
- Fed Dampens March Rate Cut Hopes
- Bank of England Cautious
- Earnings Recap
- US Employment Report Far Better than Expected
- What’s Ahead
US Stocks Up Again
U.S. stocks experienced a robust rally on Friday to build on an erratic, but overall strong week, propelling the S&P 500, Dow Jones Industrial Average, and Nasdaq Composite to new record highs. The surge was primarily fueled by outstanding performances from major technology players, including Meta Platforms, Amazon, Microsoft, and Nvidia Corp. Notably, mega-cap technology stocks, particularly in communications services, saw substantial gains, contributing to the S&P 500's best day in communications services since April. Consumer discretionary and information technology sectors also played a significant role in the market upswing.
Additionally, industrials, financials, and energy stocks ended the day on a positive note. The strong momentum followed stellar earnings results from Meta and Amazon, with Meta's shares skyrocketing by 20.5% to achieve a record high.
The overall market sentiment was buoyed by robust corporate earnings and a January employment report that indicated strong job growth, diminishing the likelihood of an immediate interest rate cut by the Federal Reserve. This marked the fourth consecutive week of gains for all three major U.S. stock indexes.
Fed Dampens March Rate Cut Hopes
Federal Reserve Chair Jerome Powell's recent remarks have cast doubt on the possibility of a March rate cut, signaling a shift from earlier expectations. The U.S. central bank, in its latest decision, opted to keep interest rates unchanged for another consecutive month, maintaining the target range for the federal funds rate at 5.25%-5.5%, a 22-year high.
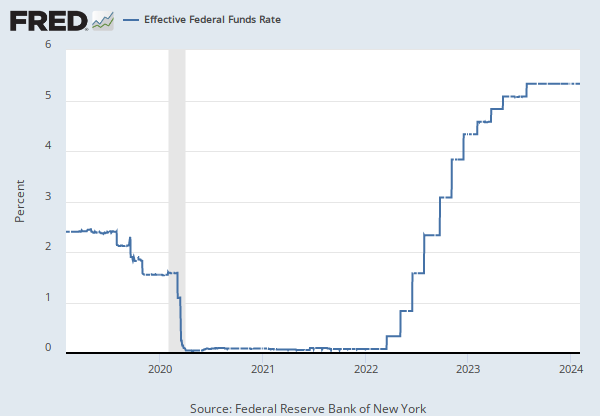
Powell emphasized the need for "greater confidence" in reaching the 2% inflation target before considering rate cuts, stating that the committee is unlikely to reach that level of confidence by the March meeting. The market response reflects a significant reduction in expectations, with CME's FedWatch tool showing a decreased likelihood of a 25 basis point rate cut in March, dropping from 69.6% to 20.5% over the past month.
Powell's cautious stance and the deliberate vagueness of the Fed's statement underscore the central bank's commitment to a data-dependent approach, leaving room for flexibility based on evolving economic conditions.
Bank of England Cautious
In the Bank of England's latest decision to maintain interest rates at a 15-year high of 5.25%, a noteworthy three-way split among policymakers emerged for the first time since 2008. The market's response was relatively muted, reflecting the Bank's emphasis on the prerequisite of acquiring more evidence indicating a favorable trajectory for inflation before contemplating any rate adjustments. The Monetary Policy Committee (MPC), composed of six members favoring a hold and two advocating for a 25 basis point hike, showcased a cautious stance. Notably, Swati Dhingra, the MPC's most dovish member, broke ranks by voting for a rate cut, marking a departure from the consensus.
Despite acknowledging a significant and relatively sharp decline in inflation over the past few months, the Bank refrained from providing a specific timetable for potential rate cuts. Governor Andrew Bailey hinted at the possibility of a downward shift in interest rates, citing the forecast that inflation would fall below 2% in the upcoming months. However, Bailey emphasized the Bank's need for greater confidence in the sustained deceleration of prices before actively considering any reductions in interest rates. This decision underscores the Bank of England's cautious approach amid lingering uncertainties and the evolving economic landscape.
Earnings Recap
Microsoft
Microsoft's 2023 Q4 earnings call, released on Tuesday, January 30th, 2024, highlighted the tech giant's robust financial performance. According to data from investing.com, Microsoft reported an earnings per share (EPS) of $2.93, surpassing the forecasted EPS of $2.78. The company's revenue for the quarter reached $62 billion, slightly exceeding the predicted revenue of $61.1 billion.
Microsoft's impressive results were attributed to strong growth in Azure cloud services, outperforming expectations. Notably, during the quarter, Microsoft completed its largest-ever acquisition, acquiring video game publisher Activision Blizzard. Despite the positive financial results, Microsoft's shares experienced a temporary dip of up to 2% in extended trading after the release of the fiscal second-quarter results. The company's revenue for the quarter increased by 17.6% year over year, with net income reaching $21.87 billion, up from $16.43 billion.
Alphabet
Alphabet's 2023 Q4 earnings call, released on Tuesday, January 30th, 2024, demonstrated solid performance, slightly surpassing expectations. According to investing.com, Alphabet reported an earnings per share (EPS) of $1.64, exceeding the forecasted $1.59. The company's revenue for the quarter amounted to $86.31 billion, outpacing the predicted revenue of $85.23 billion.
Despite the overall positive results, Alphabet's shares experienced a more than 6% decline in after-hours trading as the reported ad revenue fell short of analysts' estimates. The company faced challenges in this regard, with ad revenue of $65.52 billion missing the expected $65.94 billion, as reported by StreetAccount. Notably, YouTube, a significant contributor to Alphabet's growth, narrowly missed expectations. Despite these challenges, Alphabet's shares have experienced a notable 56% increase in the past year, excluding the after-hours adjustment, underscoring the company's resilience in the market.
Apple
Apple's 2023 Q4 earnings call, revealed on Thursday, February 1st, 2024, highlighted the tech giant's financial strength, slightly surpassing expectations. The reported earnings per share (EPS) reached $2.18, exceeding the forecasted $2.1, and the quarterly revenue hit an impressive $119.58 billion, surpassing the anticipated $118.06 billion. These robust financial outcomes underscore Apple's enduring success and market dominance.
Despite posting its first sales growth in a year, driven by record revenue from the App Store and other services, Apple faced challenges in China, with revenue in the region declining by 13%. The introduction of the Vision Pro headset, a major new product for the company, was accompanied by concerns about slowing demand in China, possibly due to rising competition from local companies. While Apple's CEO, Tim Cook, expressed optimism about China's long-term prospects, questions linger about the impact of rising interest rates and a weaker economic backdrop on consumer purchasing behavior.
Amazon
Amazon's Q4 2023 earnings call, unveiled on February 1st, 2024, showcased the e-commerce behemoth's financial prowess. The reported earnings per share (EPS) surpassed expectations at $1, compared to the forecasted $0.8, while the quarter's revenue reached an impressive $170 billion, outperforming the anticipated $165.95 billion. These stellar financial outcomes underscore Amazon's continued dominance in online retail and its adept navigation of diverse business segments.
The company's performance exceeded analysts' expectations for fourth-quarter earnings and revenue, reflecting its ability to adapt and excel in various sectors. Despite laying off 27,000 employees between late 2022 and mid-2023 and streamlining certain business units, Amazon's strategic decisions have contributed to its financial success. CFO Brian Olsavsky emphasized a careful approach to new investments in 2024, balancing efficiency measures with ongoing innovation. The company remains optimistic, with CEO Jassy noting the record-breaking Holiday shopping season and expressing excitement about the prospects ahead in 2024.
Meta
Meta's Q4 earnings call for 2023, unveiled on Thursday, February 1st, 2024, exceeded expectations and triggered a substantial surge in the social media giant's stock. The reported earnings per share (EPS) came in at $5.33, surpassing the forecasted $4.96, while the quarterly revenue reached $40.11 billion, outperforming the expected $39.02 billion, according to data from investing.com.
Meta's market capitalization soared by $197 billion to $1.2 trillion, marking a remarkable 20.3% increase. This surge, coupled with the announcement of Meta's first-ever quarterly dividend, set new records by surpassing the one-day market cap gains of Amazon and Apple in 2022. The robust financial results and positive outlook reinforced Wall Street's confidence in Big Tech's ability to achieve profitable growth while investing heavily in artificial intelligence, despite workforce reductions undertaken in the previous year.
US Employment Report Far Better than Expected
The US employment report for January exceeded expectations, revealing the addition of an impressive 353,000 jobs, well above the Dow Jones estimate of 185,000. This robust job growth, along with a notable uptick in wage growth, showcases the resilience of the US labor market and its potential to support broader economic expansion. The unemployment rate remained steady at 3.7%, in line with estimates. Average hourly earnings experienced substantial growth, increasing by 0.6%—double the monthly estimate—and marking a substantial year-over-year rise of 4.5%, surpassing the forecasted 4.1%. Job gains were widespread across sectors, with professional and business services leading at 74,000, followed by health care (70,000), retail trade (45,000), government (36,000), social assistance (30,000), and manufacturing (23,000).
The report also revised December's job gains upward to 333,000, highlighting the continued strength in employment. This positive economic performance, however, may raise questions about the timing of potential interest rate adjustments by the Federal Reserve. The impressive job creation in January, coupled with the acceleration in wage growth, underscores the robust momentum of the US economy, prompting attention from economists and policymakers alike. While recent high-profile layoffs have raised concerns, broader indicators, such as initial jobless claims, suggest a reluctance among companies to part with workers in the tight labor market. The unexpected strength in the job market positions the US economy favorably and adds momentum following the record-setting job creation in December 2023.
What's Ahead
Central Bank Watch: A quiet week for central banks, with the Reserve Bank of Australia (RBA) Interest Rate Decision, Statement and Press Conference, plus as always a focus on Fed speakers.
Macro Data Watch: Also, a quiet week for data. The focus for the week will be Monday’s Services and Composite PMI data.
Earnings Watch: A quieter for earnings as the reporting season winds down, with standouts of McDonald’s, Eli Lilly, Uber, AstraZeneca and Pepsi.
Date
Major Macro Data
02/05/2024
Global Services and Composite PMI, US ISM Services PMI
02/06/2024
RBA Interest Rate Decision, Statement and Press Conference, EU Retail Sales (MoM, YoY)
02/07/2024
Nothing of note
02/08/2024
China CPI (MoM, YoY) and PPI (YoY)
02/09/2024
German Consumer Prices (MoM, YoY), Canada Employment report
Date
Major Earnings Data
02/05/2024
McDonald’s, Caterpillar, Sony
02/06/2024
Eli Lilly, Linde, Amgen
02/07/2024
Walt Disney, Uber
02/08/2024
AstraZeneca, Philip Morris, S&P Global
02/09/2024
Pepsi
