Week commencing October 5th 2026
TradeDay Macro Matters
Macroeconomic / Geopolitical developments
- US stock averages mixed for the week, as UST yields stay high and oil prices chop
- US jobs report worse than forecast, easing rate hike expectations
- PCE inflation and Manufacturing PMI data steady
- Fed Minutes and Services PMI in the spotlight
- What's Ahead
US stock averages mixed for the week, as UST yields stay high and oil prices chop
US stocks ended the week mixed, with the Nasdaq Composite gaining 0.45%, while the S&P 500 slipped 0.27% and the Dow Jones Industrial Average fell 1.26%. The Nasdaq continued to outperform, supported by strength in technology stocks, which gained 1.44%, while energy also advanced 1.21%. Healthcare and financial services stocks were among the weakest sectors, falling 2.57% and 2.45% respectively.
Despite the weaker performance from the broader market, investors continued to contend with elevated borrowing costs as Treasury yields remained close to multi decade highs. The 10 year Treasury yield rose to 5.28% from 5.17%, while West Texas Intermediate crude fell 1.13% to $91.40 a barrel, adding another layer of uncertainty for markets as investors weighed the competing effects of high yields and volatile energy prices.
US jobs report worse than forecast, easing rate hike expectations
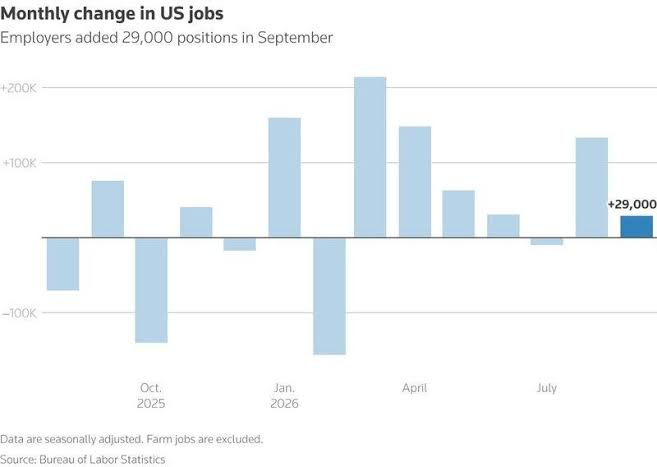
The US labor market weakened noticeably in September, with employers adding just 29,000 jobs compared with expectations of around 84,000 to 90,000. The unemployment rate also increased to 4.2% from 4.1%, while payroll figures for July and August were revised lower by a combined 60,000, reinforcing signs that hiring momentum has slowed.
The weaker employment figures prompted markets to scale back expectations for another Federal Reserve rate increase later this month. Rate futures moved to imply around a 79% probability of the Fed holding rates steady at its October meeting, compared with 64% a week earlier, while annual wage growth slowed to 3%, its lowest level since May 2021.
PCE inflation and Manufacturing PMI data steady
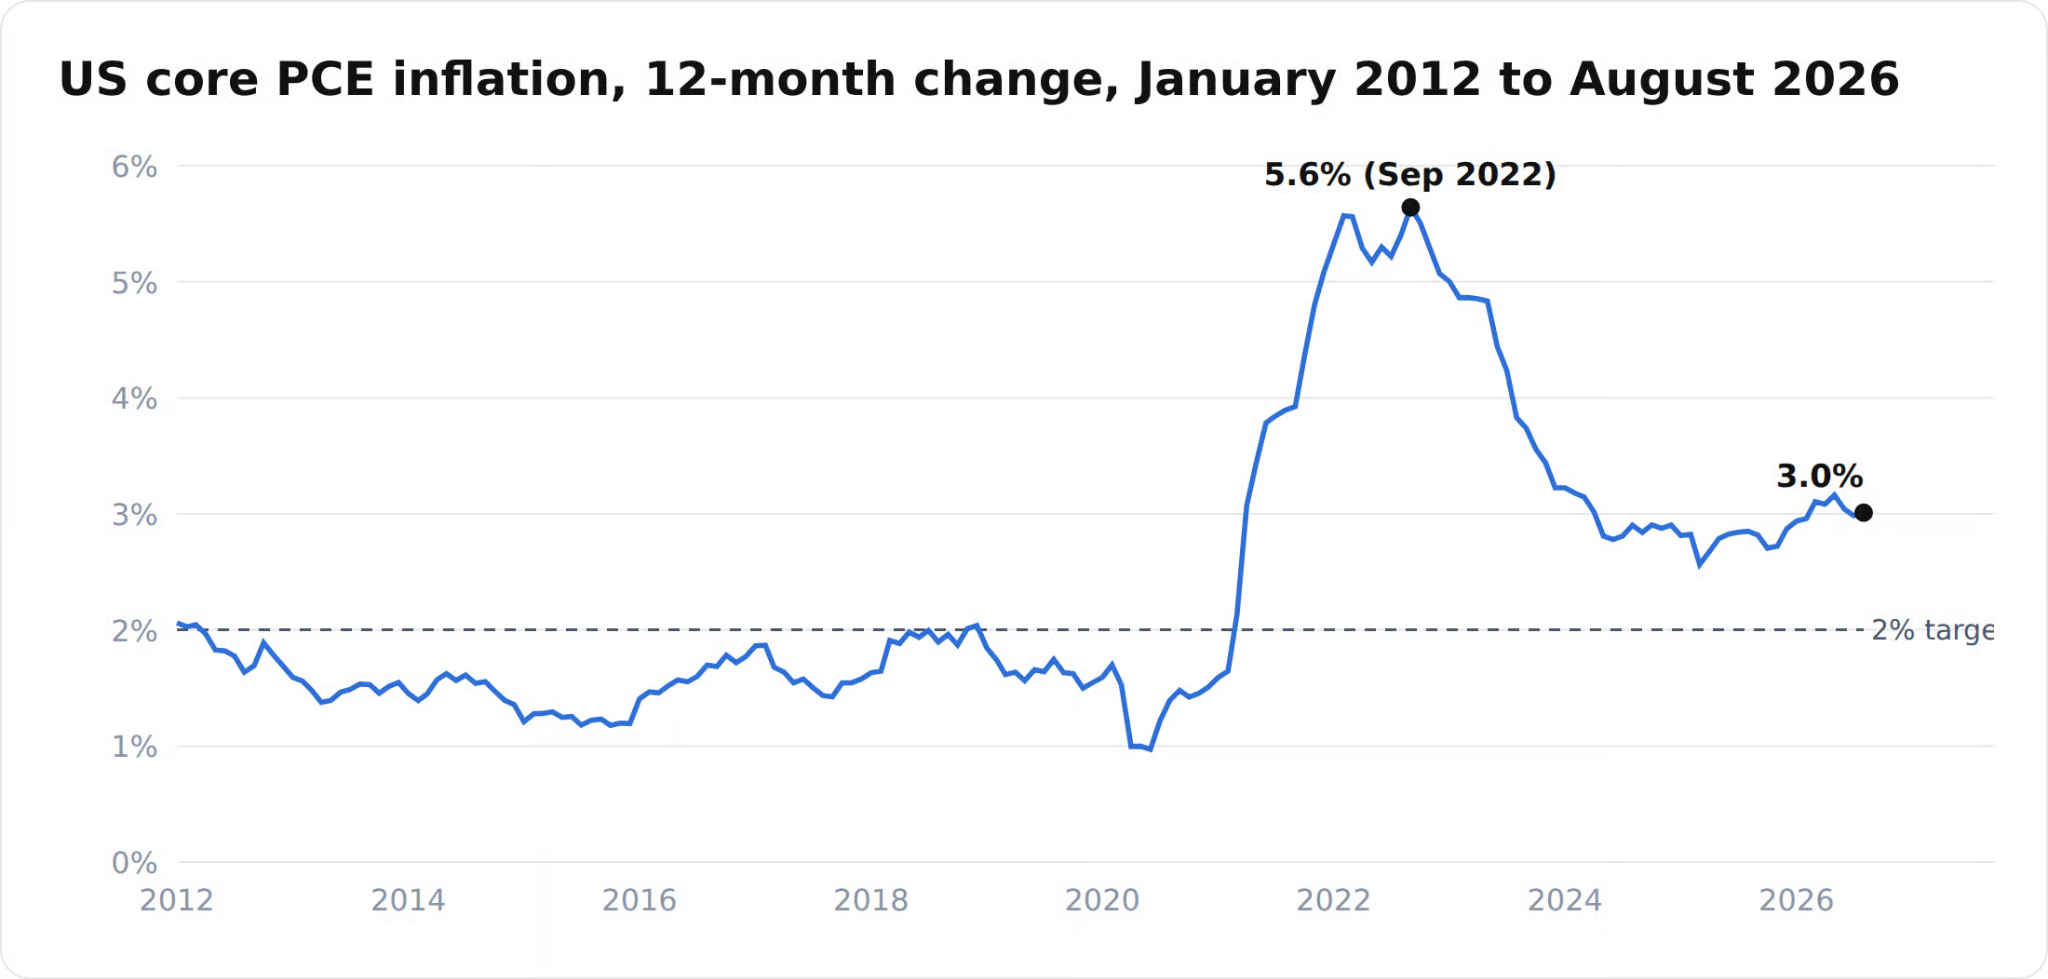
The Federal Reserve’s preferred inflation measure provided some relief, with headline PCE inflation rising 3.4% year over year in August, below expectations of 3.7%. Core PCE, which excludes food and energy, increased 3.0% annually, also below forecasts, while the three month annualized rate reached 2%, suggesting that underlying price pressures have been easing.
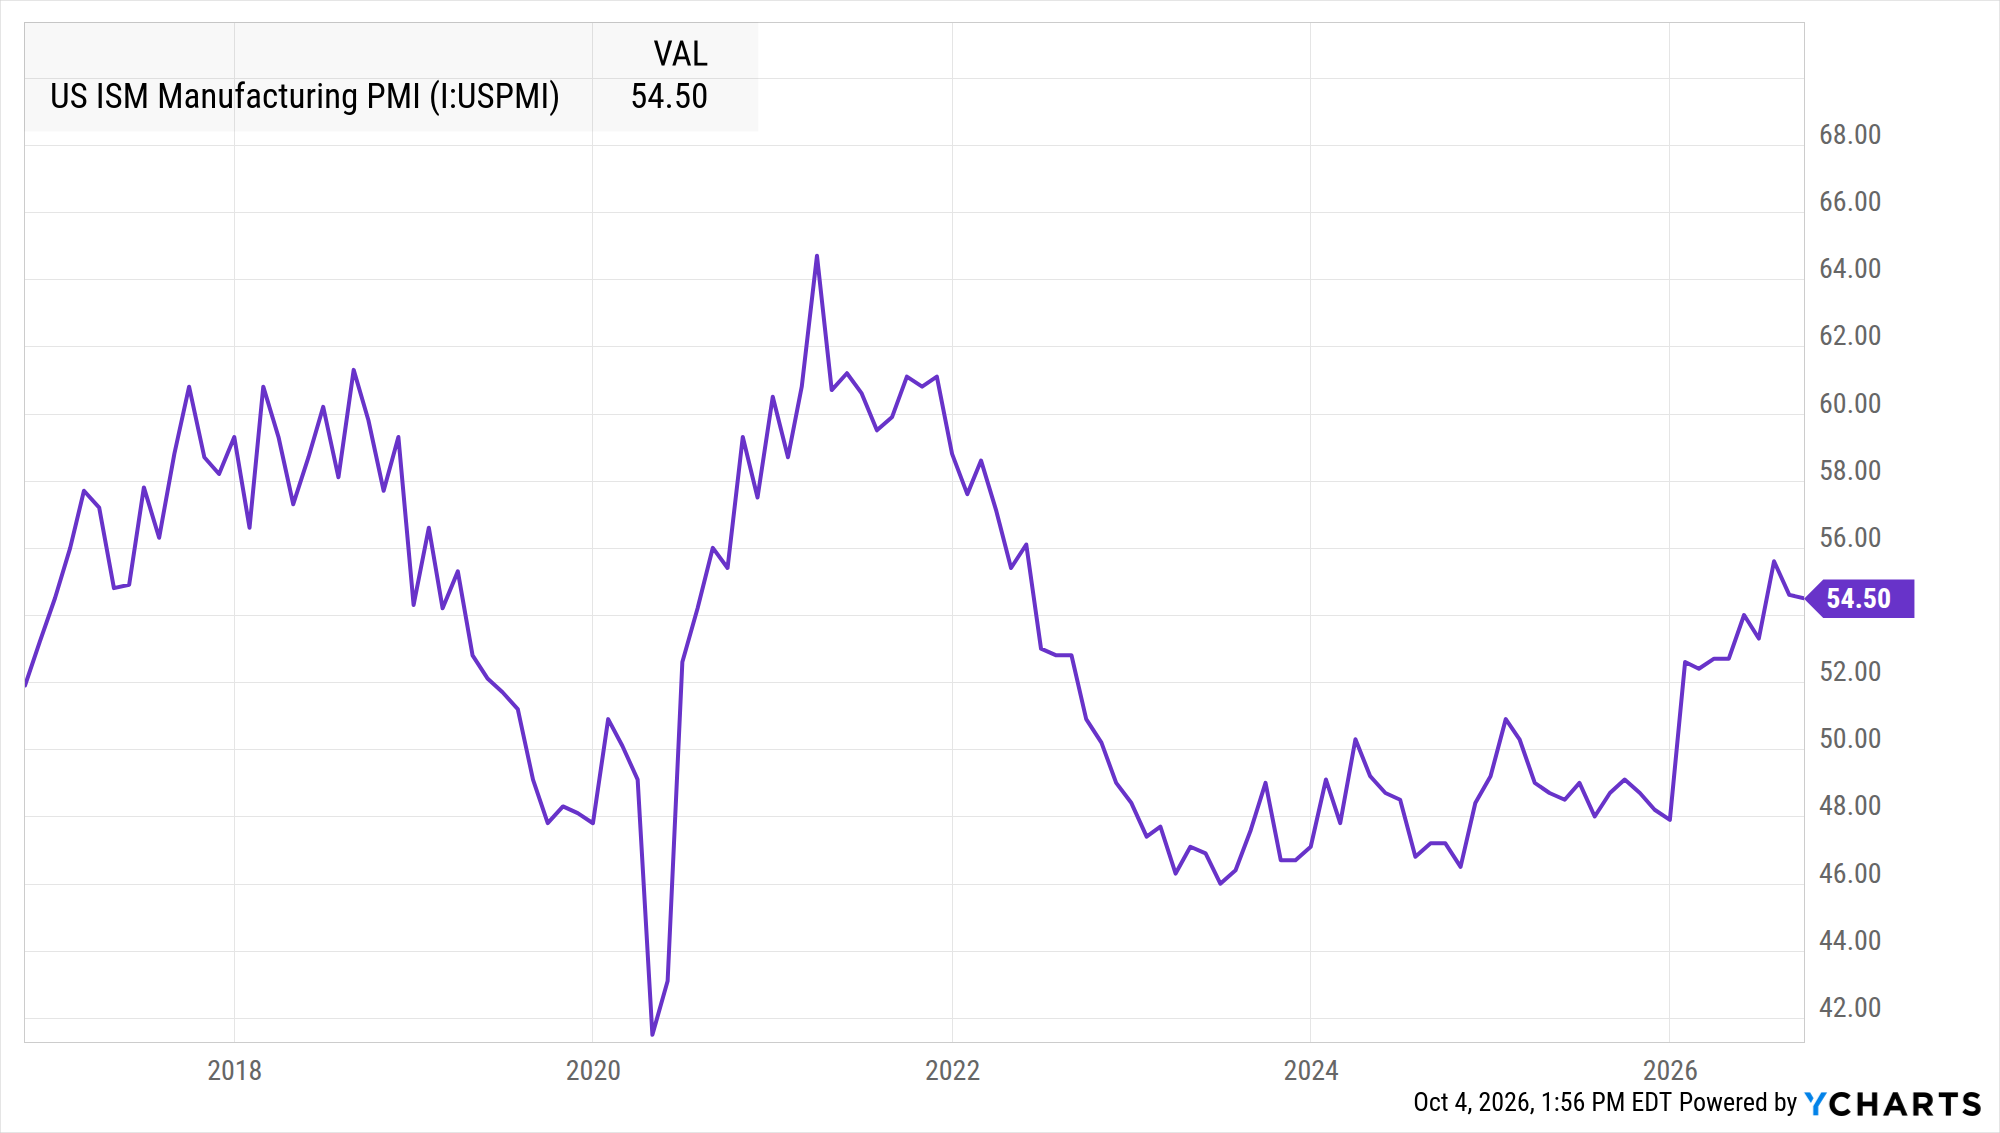
US manufacturing remained firmly in expansion territory, with the ISM Manufacturing PMI registering 54.5 in September, broadly unchanged from August and marking a ninth consecutive month of expansion. However, the prices index jumped 6.8 points to 77.9, its highest level since May, highlighting renewed pressure on manufacturers’ input costs even as new orders and employment strengthened.
Fed Minutes and Services PMI in the spotlight
Attention now turns to the September Federal Reserve meeting minutes, which could provide greater detail on policymakers’ thinking following the latest rate increase. Investors will be looking for clues about how officials view inflation, the labor market and the potential need for further rate increases, particularly after the latest softer employment and inflation data.
The September Services PMI will also be closely watched on Monday, with services accounting for the largest share of US economic activity. August data showed strong demand but weaker employment and elevated prices, so investors will be watching whether September confirms resilient activity alongside continued cost pressures, while jobless claims and consumer sentiment will provide additional insight into the health of the economy.
What's Ahead
Central Bank Watch: The main central bank activity this week is the FOMC Minutes on Wednesday.
Macro Data Watch: The main macro data release this week is the Global Service and Composite PMI on Monday. Some other releases of note are the EU Retail Sales on Tuesday, Canadian Employment report and Michigan Consumer Sentiment Index both on Friday.
Date
Major Macro Data
10/05/2026
Global Service and Composite PMI; EU Sentix Investor Confidence and PPI
10/06/2026
German Factory Orders; EU Retail Sales
10/07/2026
FOMC Minutes; German Industrial Production
10/08/2026
US Initial Jobless Claims
10/09/2026
Canadian Employment Report; US Michigan Consumer Sentiment Index and Consumer Inflation Expectations
